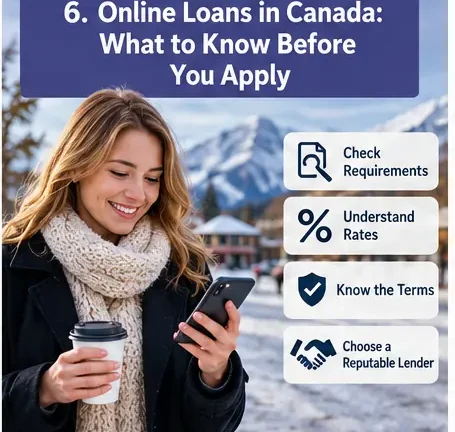
 Applying for credit online can seem straightforward, especially when a website offers a short application form and advertises a quick lending decision. Nevertheless, accepting a loan is an important financial commitment that deserves careful research. Canadians who are considering fast online loans in Alberta should evaluate their eligibility, understand the associated fees, verify the lender’s legitimacy, and consider how repayment will affect their finances before submitting an application.
Understand Your Current Financial Position
The first step is to assess your income, expenses, savings, and outstanding debts.
Lenders may review this information during the application process, but applicants should conduct their own assessment before borrowing.
Calculate how much money remains after paying necessary living expenses.
Include existing loan payments, credit card minimum payments, insurance, transportation, and household bills.
If little or no money remains each month, an additional repayment obligation could be difficult to manage.
Knowing your actual financial position helps determine whether a loan is appropriate.
Review the Available Loan Products
The phrase online loan can describe several types of credit.
Personal instalment loans generally involve structured repayments over an agreed period. Payday loans are smaller, short-term products with relatively high borrowing costs.
Lines of credit may provide more flexibility for qualified borrowers, although they can also encourage ongoing borrowing when balances are not managed carefully.
Each product serves a different financial purpose.
For example, a short-term loan with a large repayment due in several weeks may be unsuitable for someone whose income barely covers existing expenses.
Comparing multiple loan structures helps identify the risks associated with each option.
Know How Eligibility Is Assessed
Lenders commonly review identity, income, banking information, and other relevant financial details.
Certain products may require a credit assessment, while other lenders may emphasize current income and the ability to meet repayment obligations.
Requirements vary between institutions.
An applicant with imperfect credit may still have financing options, but availability and terms depend on the lender’s policies.
Consumers should be especially cautious about claims of guaranteed approval regardless of income or financial circumstances.
Responsible lenders must consider whether applicants meet their lending criteria.
Identify Every Borrowing Charge
Before signing an agreement, review all interest charges, borrowing fees, and other disclosed costs.
Pay particular attention to the total amount that must be repaid.
For payday loans covered by provincial regulatory systems, the maximum borrowing fee is generally $14 for every $100 borrowed.
A borrower receiving $400 from a payday lender charging the maximum would owe $456 at the scheduled repayment date, excluding any additional consequences associated with default.
The short repayment period can create substantial financial pressure even when the dollar amount of the fee seems relatively small.
Personal instalment loans have different pricing structures, making it important to examine their annual percentage rates and overall repayment costs.
Protect Sensitive Personal Information
Online applications often involve sharing private financial information.
Before submitting documents, verify that the lender’s website is legitimate and that the business is properly identified.
Review its privacy policies and research the company’s reputation.
Be especially careful when asked to enter online banking credentials.
Fraudulent lending websites may imitate legitimate financial institutions or use misleading verification processes to collect sensitive information.
Never disclose passwords through suspicious links or respond to unexpected messages requesting one-time security codes.
If something appears unusual, contact the financial institution through an independently verified channel.
Read the Terms Before Accepting
A loan offer may contain important conditions that are not highlighted in the original advertisement.
Examine the repayment dates, withdrawal authorization, late-payment consequences, cancellation conditions, and any restrictions on changing payment arrangements.
Ask for clarification if the agreement contains unfamiliar terminology.
Where provincial law provides cancellation rights or other consumer protections, borrowers should understand how those rights can be exercised.
A legitimate lending offer should provide an opportunity to review the terms before making a commitment.
Prepare for Unexpected Changes
Even a carefully planned repayment schedule can be affected by unforeseen events.
Reduced working hours, illness, additional household expenses, or a delayed paycheque can change the amount available for repayment.
Consider whether the loan would remain manageable under less favourable circumstances.
If one missed paycheque would make repayment impossible, the borrowing arrangement may be too risky.
Before accepting the loan, compare lower-cost alternatives and develop a clear repayment plan.
Financial decisions made before an application is submitted can be just as important as the lender’s eventual decision.